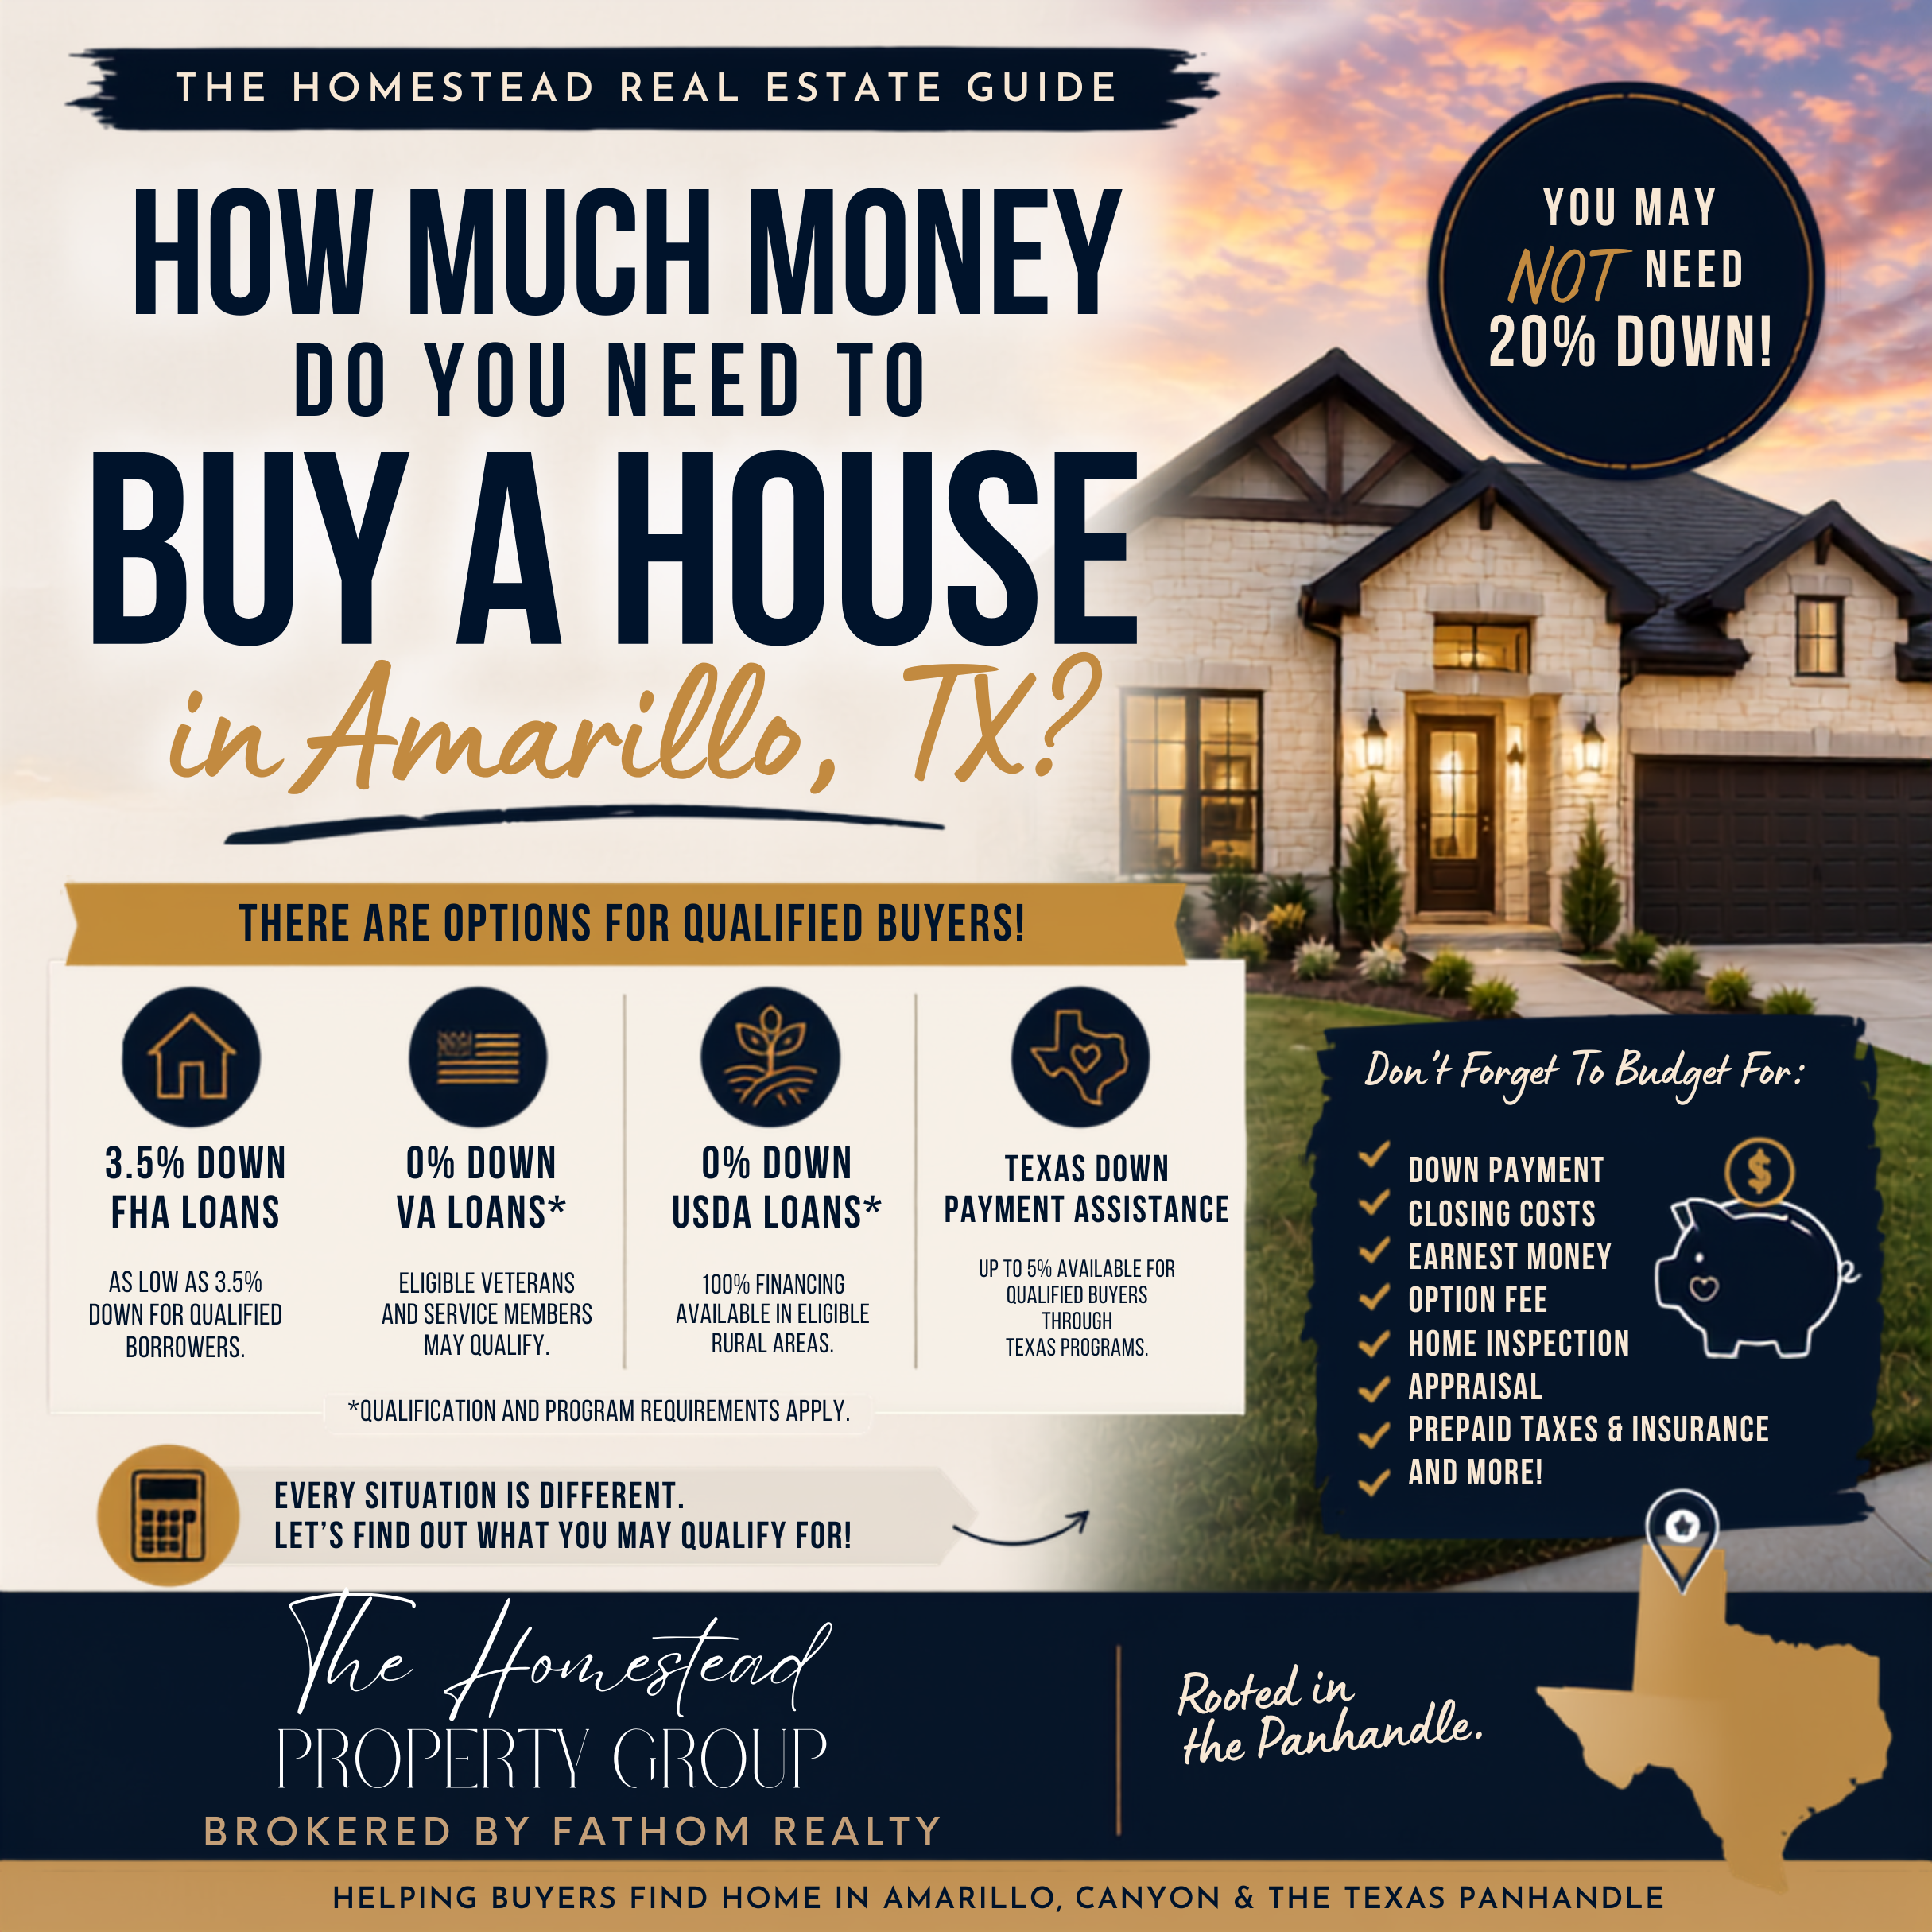
How Much Money Do You Need to Buy a House in Amarillo, TX?
If you're thinking about buying a home in Amarillo, one question probably comes to mind pretty quickly:
How much money do I actually need?
For many first-time buyers, the number they have in their head is much higher than what may actually be required.
One of the biggest misconceptions we hear is:
"I need 20% down before I can buy a house."
That simply isn't true for every buyer.
Depending on your qualifications, loan program, the property you're purchasing and available assistance programs, you may be able to buy a home with a relatively small down payment—or, in certain situations, no down payment at all.
But your down payment isn't the only expense you need to consider.
Let's break down what Amarillo homebuyers should actually plan for when preparing to purchase a home.
The Quick Answer: How Much Money Do You Need?
There isn't one number that applies to everyone.
The cash you may need to purchase a home can include:
Down payment
Earnest money
Option fee
Home inspection
Appraisal
Closing costs
Prepaid taxes and insurance
Other lender or transaction expenses
However, some of these expenses may potentially be reduced through loan programs, seller concessions, builder incentives or down-payment and closing-cost assistance.
That's why we tell buyers:
Don't assume you can't afford to buy until you've actually talked with a knowledgeable lender.
You may be much closer than you think.
Do You Need 20% Down to Buy a House in Amarillo?
No.
Putting 20% down can have advantages, but it is absolutely not a universal requirement for purchasing a home.
Depending on your qualifications, financing options can include FHA, conventional, VA and USDA loans, along with various homebuyer-assistance programs.
Each program has different requirements.
Your lender should help determine which options fit your income, credit, debt, available savings and the property you're purchasing.
How Much Is an FHA Down Payment?
For qualified borrowers, an FHA loan can allow a down payment as low as 3.5% of the purchase price.
For example, on a $250,000 home:
3.5% = $8,750
That is significantly different from the $50,000 someone might assume they need if they believe a 20% down payment is required.
FHA loans have additional requirements and costs, including mortgage insurance, so the smallest possible down payment isn't automatically the best financial choice for every buyer.
That's a conversation to have with your lender.
Can You Buy a Home With 0% Down?
Some buyers can.
Two important programs to know about are VA and USDA financing.
VA Loans
Eligible Veterans, service members and certain surviving spouses may qualify for a VA-backed home loan.
For qualified borrowers with sufficient entitlement, VA financing can often allow a home purchase without a down payment, provided the property and transaction meet applicable requirements.
USDA Loans
USDA financing can provide eligible buyers with 100% financing on qualifying properties in eligible rural areas.
This can be particularly interesting in the Texas Panhandle because buyers sometimes assume "rural" means living extremely far from Amarillo.
Depending on current USDA eligibility maps and the specific property, locations surrounding Amarillo may qualify.
Your lender should verify both borrower and property eligibility before you rely on USDA financing for a particular home.
What About Conventional Loans?
Conventional financing doesn't automatically mean 20% down either.
Depending on the specific loan program and borrower qualifications, some conventional buyers may qualify with much less.
However, your down payment can affect your:
Monthly payment
Loan amount
Mortgage insurance
Interest rate and loan terms
Cash remaining after closing
This is why we don't recommend choosing a down payment amount solely because it's the lowest amount technically available.
Sometimes keeping additional savings after closing is more important than putting every available dollar into the house.
Your lender can help you compare different scenarios.
Are There Down-Payment Assistance Programs in Texas?
Yes.
Qualified Texas homebuyers may have access to programs that help with down payment and closing costs.
The Texas Department of Housing and Community Affairs offers programs including My First Texas Home and My Choice Texas Home.
My First Texas Home
This program is designed for qualifying first-time homebuyers and certain qualified Veterans and can offer assistance toward down payment and closing costs.
My Choice Texas Home
This program does not require you to be a first-time homebuyer.
Qualified first-time buyers, repeat buyers and Veterans may potentially use the program.
Current TDHCA materials show assistance options of up to 5% of the mortgage amount, subject to program requirements and availability.
That doesn't mean everyone automatically qualifies.
Income limits, credit requirements, loan requirements, homebuyer education and other guidelines may apply.
But this is exactly why we encourage buyers to explore their options before deciding homeownership is out of reach.
Let's Look at a $250,000 Amarillo Home
Recent 2026 housing data has put Amarillo's median sale price around $250,000, so let's use that as a simple example.
20% Down
Purchase price: $250,000
20% down: $50,000
10% Down
Purchase price: $250,000
10% down: $25,000
5% Down
Purchase price: $250,000
5% down: $12,500
3.5% Down
Purchase price: $250,000
3.5% down: $8,750
0% Down
For a buyer who qualifies for an eligible zero-down loan program:
Down payment: $0
But here's the important part:
Down payment is NOT the same thing as total cash needed to close.
You may still have closing costs, prepaid expenses, inspections and other transaction costs even if your loan doesn't require a down payment.
What Are Closing Costs?
Closing costs are separate from your down payment.
They can include expenses associated with your mortgage, title work, appraisal, prepaid insurance, taxes and other parts of completing the transaction.
The exact amount varies significantly depending on:
Purchase price
Loan type
Lender
Insurance
Property taxes
Closing date
Negotiated seller contributions
Other transaction-specific expenses
Rather than relying on a generic online percentage, ask your lender for a personalized estimate based on your actual financing scenario.
That gives you a much more useful number.
Can the Seller Help Pay Closing Costs?
Potentially, yes.
Depending on your loan program, contract terms and market conditions, you may be able to negotiate for the seller to contribute toward certain allowable buyer expenses.
This is one reason having a real estate agent and lender communicating before an offer is written can be so valuable.
Instead of simply asking:
"How low can we get the price?"
sometimes the better question is:
"How can we structure this offer to help the buyer accomplish their overall financial goal?"
For a buyer who has enough income to comfortably afford the monthly payment but wants to preserve cash, seller concessions can sometimes be more valuable than a small reduction in purchase price.
Every transaction is different, which is why strategy matters.
What About Builder Incentives?
If you're considering new construction in Amarillo or Canyon, builder incentives can make a significant difference in your upfront costs.
Depending on the builder and current promotion, incentives may potentially be used toward things such as:
Closing costs
Interest-rate buydowns
Certain upgrades
Other allowable expenses
Builders may also offer additional incentives for using a preferred lender.
That doesn't automatically mean the builder's lender is the best choice.
We encourage our buyers to compare the entire financial picture—interest rate, closing costs, incentives, loan terms and monthly payment—before deciding.
What Are Earnest Money and the Option Fee?
These are two other upfront expenses Texas buyers should understand.
Earnest Money
Earnest money is money delivered after the contract is executed as part of the buyer's contractual obligations.
It demonstrates the buyer's commitment to the transaction and is generally handled according to the terms of the contract.
Option Fee
In many Texas resale transactions, a buyer may pay an option fee for the contractual right to terminate during an agreed option period.
This is commonly when buyers complete inspections and evaluate whether they want to continue with the purchase.
The amount of earnest money, option fee and length of the option period are negotiable contract terms.
We'll explain exactly what you're agreeing to before you sign an offer.
Don't Forget the Home Inspection
Your inspection is another expense you'll generally want to budget for.
Inspection pricing varies depending on the property and services needed.
A larger home, acreage property, septic system, well or other specialized features may require additional inspections.
We consider inspections an important part of helping buyers understand what they're purchasing.
Even new-construction buyers should consider having an independent inspection.
Should You Spend All Your Savings on the Down Payment?
Usually, we want our buyers to think beyond closing day.
Owning a home means things eventually need attention.
Appliances break.
HVAC systems need service.
A sprinkler head decides it has other plans.
And sometimes you move in and immediately realize you absolutely NEED a new couch for the living room. 😂
Keeping an emergency fund after closing can be extremely valuable.
This is another reason the "largest down payment possible" isn't automatically the right strategy.
Talk with your financial and lending professionals about what makes sense for your situation.
What If You Don't Have Much Saved Yet?
Still start the conversation.
Seriously.
We've talked to buyers who waited because they assumed they weren't ready when what they really needed was a plan.
Maybe you're ready now.
Maybe you need three months.
Maybe you need six months.
Maybe you need a year.
A good lender can help identify what needs to happen between where you are today and where you need to be to purchase.
Then we can help you understand the real estate side while you work toward that goal.
You don't have to be ready to buy tomorrow to start preparing today.
What Should You Do First?
Before deciding how much house you can afford based on an online calculator, talk with a lender.
Ask them to show you multiple scenarios.
For example:
What does $225,000 look like monthly?
What does $250,000 look like?
What happens if I put 3.5% down vs. 5%?
Do I qualify for assistance?
Could USDA or VA financing apply to me?
What would my estimated total cash to close be?
Then decide which payment and cash requirement actually feels comfortable.
Your maximum approval amount and your comfortable budget do not have to be the same number.
Frequently Asked Questions
How much do I need for a down payment on a house in Amarillo?
It depends on your financing. Some qualified FHA borrowers may put as little as 3.5% down, conventional options can require considerably less than 20%, and eligible VA or USDA buyers may have zero-down options.
Can I buy a house in Amarillo with $10,000 saved?
Potentially. Whether $10,000 is enough depends on the home price, loan program, closing costs, seller concessions, assistance programs and other transaction expenses. A lender can calculate this based on your individual situation.
Can I buy a house with no money down in Amarillo?
Certain qualified buyers may be eligible for zero-down VA or USDA financing. Down-payment assistance may also reduce the amount some buyers need upfront. Zero down does not necessarily mean zero dollars out of pocket for the entire transaction.
Do first-time buyers get down-payment assistance in Texas?
Qualified buyers may have access to Texas homebuyer programs that provide down-payment and closing-cost assistance. Program requirements include eligibility guidelines and may change over time.
Do I need 20% down to avoid PMI?
Private mortgage insurance is generally associated with conventional loans when the borrower has less than a certain amount of equity. However, mortgage-insurance rules vary by loan type. Your lender can explain how different down payments affect your specific loan.
Should I talk to a REALTOR® or lender first?
Either conversation can be a good starting point.
If you contact us first, we can connect you with trusted lenders who can evaluate your financing options.
If you've already been pre-approved, even better—we can begin building your home-buying plan from there.
Wondering If You're Ready to Buy?
You don't need $50,000 sitting in the bank before you're allowed to ask the question.
And you don't need perfect knowledge of mortgages before contacting us.
At The Homestead Property Group, we believe buying confidently starts with understanding your options.
We'll help you connect with the right professionals, understand the Amarillo market and develop a plan based on your actual situation.
Whether you're ready today or preparing for next year, we'd rather help you create a roadmap than have you spend another year assuming homeownership isn't possible.
Let's find out what's possible.
Contact The Homestead Property Group to start your Amarillo home-buying plan.
Author:
Madison Carney, REALTOR®
The Homestead Property Group, brokered by Fathom Realty
Published August 2026 | Updated regularly with Amarillo and Canyon real estate information
Check out this article next